Travel insurance for China should match your actual itinerary, health situation and planned activities—not just carry the word “China” on a sales page. Before buying, check that the policy is valid for your residence and age, covers every day and destination on the trip, includes emergency medical treatment plus evacuation and repatriation, and does not exclude an activity or condition that matters to you.
Official UK travel guidance says healthcare in China is not free and can be expensive. It recommends insurance covering healthcare, medical evacuation and repatriation. A hospital may still ask for a deposit or payment even when you have insurance, so keep access to emergency funds and save every receipt and medical record.
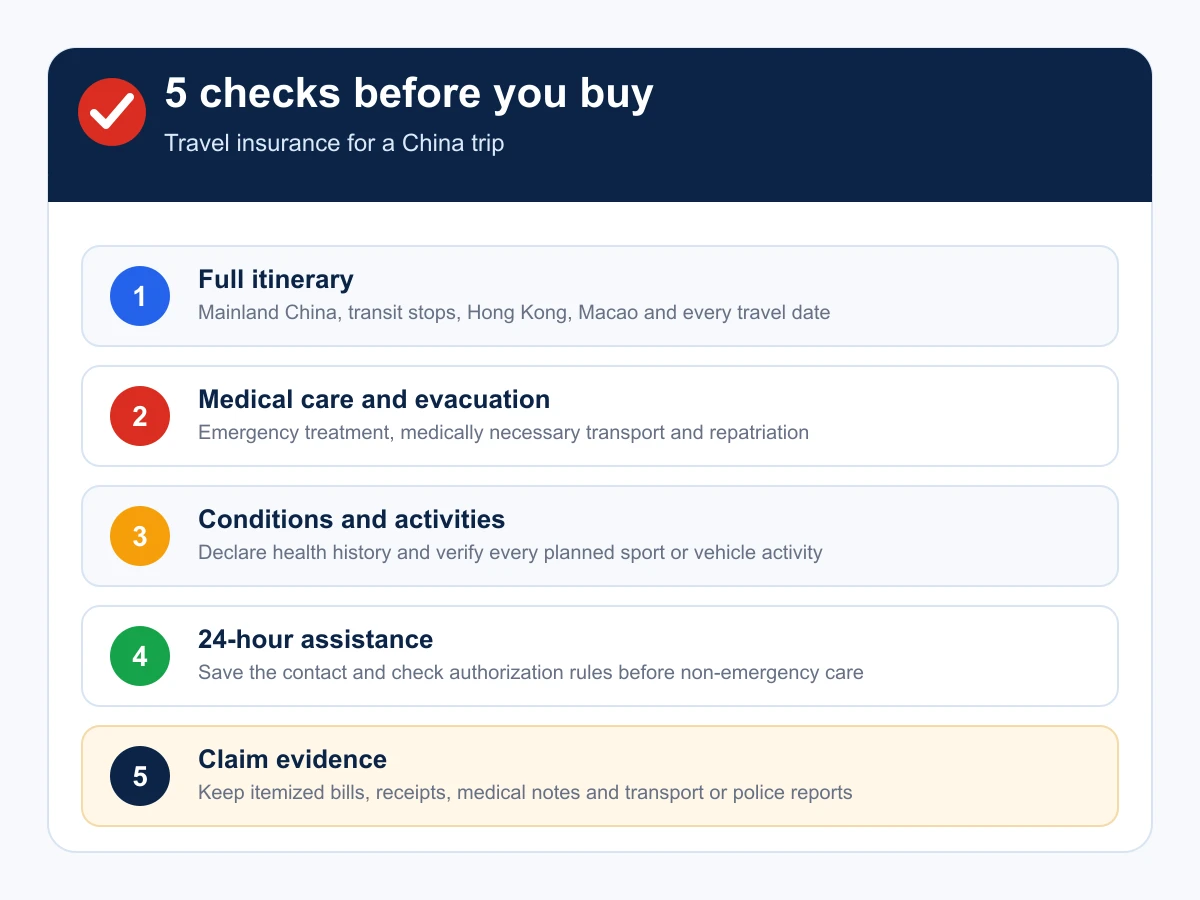
A Five-Point China Travel Insurance Check
Use these questions before comparing brands or prices:
- Does it cover your full itinerary? Include mainland China, transit countries, Hong Kong, Macao and any side trip separately. Do not assume that one geographic label covers every stop.
- What medical help is included? Check emergency outpatient and inpatient care, hospital treatment, medically necessary evacuation and repatriation.
- Are your conditions and activities covered? Declare health conditions accurately and check the exact rules for hiking, skiing, cycling, scooter or motorbike use, and any other planned activity.
- How does assistance work? Save the 24-hour assistance number and find out which treatment, admission or evacuation requires advance authorization.
- What evidence will a claim need? Confirm deadlines and keep itemized invoices, proof of payment, medical notes, diagnoses, prescriptions, carrier reports and police reports when relevant.
The cheapest policy can be poor value if it excludes the event you are most likely to claim for. Compare the policy wording, not only a benefit summary or headline limit.
What China Travelers Should Prepare for
China’s healthcare and payment process can create a practical gap between “insured” and “treatment paid for.” Official guidance warns that hospitals may require a deposit even when a traveler has insurance. International cards are not accepted everywhere, and a provider listed in an insurer’s directory is not proof that every service will be cashless or covered.
Before departure:
- Save the policy certificate, policy number and assistance contact offline.
- Ask the insurer how to find an appropriate provider in each destination.
- Keep a payment backup for a hospital deposit or other upfront cost.
- Ask whether non-emergency treatment, inpatient care or evacuation needs authorization.
- Save the insurer’s claim instructions and document checklist.
- Put the policy details and emergency contacts in your First 72 Hours in China offline plan.
In a serious emergency, seek urgent help first and contact the insurer as soon as practicable. Mainland emergency numbers include ambulance 120, police 110, fire 119 and traffic police 122. Recheck them against current official travel advice before departure.
Medical Coverage, Evacuation and Repatriation
These three terms solve different problems.
Emergency medical coverage can address eligible treatment for a new illness or injury, subject to the policy’s deductible, limits, medical-necessity rules, exclusions and reasonable-charge provisions.
Medical evacuation generally means medically necessary transport arranged or approved under the policy. It is not a cash allowance that automatically reimburses any flight or ambulance you book yourself. Contact the assistance team as early as possible unless immediate emergency care makes that impossible.
Repatriation can cover an eligible return to a home country after a serious medical event or the return of remains after death. Read the exact wording because triggers and arrangements differ.
Do not assume that a high headline medical limit removes sublimits, deductibles, authorization rules or exclusions.
Pre-Existing Conditions and Planned Activities
Pre-existing-condition definitions vary by insurer, product and sometimes policy version. A definition may look back at diagnosis, treatment, medication, symptoms or medical advice before coverage starts. Disclose accurately and ask for written confirmation if a condition matters to your decision.
Activity cover also needs an exact check. A policy may include ordinary sightseeing but exclude or restrict a higher-risk activity. Motor incidents can depend on licensing, safety equipment and sobriety. Never rely on a generic “sports covered” label for hiking, skiing, diving, cycling or scooter use.
Other common limits can involve alcohol or drugs, illegal acts, medical tourism, known events, travel against official advice and costs already reimbursed elsewhere. The full exclusion section matters more than a short comparison table.
Trip Cancellation, Delay and Baggage Are Not Automatic
Trip cancellation usually covers named events, not a change of mind. Confirm:
- which reasons qualify;
- when coverage must be purchased;
- whether illness affecting a traveler or close relative is covered;
- what evidence is required;
- whether airline, hotel or other refunds are deducted first;
- the benefit limit and any deductible.
Travel-delay and baggage benefits also have waiting periods, per-item limits and documentation rules. Keep airline or rail statements, baggage reports and receipts for necessary replacement purchases. Do not buy a medical-focused policy assuming it automatically provides broad cancellation protection.
SafetyWing Essential vs Complete
SafetyWing is one option to compare, but its two products serve different needs. The information below was checked on September 28, 2026 and must be verified again in the live quote, certificate and policy documents.
| Question | Nomad Insurance Essential | Nomad Insurance Complete |
|---|---|---|
| Core purpose | Travel medical insurance for new, unexpected issues while traveling, with selected travel benefits | Annual international health insurance plus a separate package of travel benefits |
| More natural fit | A defined China trip, subject to eligibility and terms | A nomad, expat or long-term international resident seeking broader ongoing healthcare |
| Timing | Can be bought before departure or while abroad, subject to current start rules | Application can take time; the published process does not create immediate cover |
| Duration | SafetyWing currently describes an active period of up to 364 days | The health policy is a 12-month commitment; the travel portion uses a separate active-period framework |
| Routine care | Centered on new, unexpected travel medical needs | Broader health benefits can include routine and preventive care, subject to waiting periods and limits |
| Existing conditions | Generally excluded under a policy-version-specific definition | Disclosure and underwriting control; never assume a condition will be covered |
| Hong Kong side trip | Check the live quote and certificate separately | Current wording treats Hong Kong as a geography that may require the relevant add-on |
Essential is the closer product-category match for many short China holidays. Complete should not be presented as a simple upgrade: it combines international health insurance with travel benefits, uses an application process and carries a 12-month commitment.
SafetyWing has a China medical-provider directory, which supports that mainland China is within its operating footprint. That directory is not a promise that every hospital, treatment or claim is covered. Eligibility, the selected geographic area, sanctions, travel warnings, exclusions and the issued certificate still control.
This comparison does not quote a price or promise a benefit limit because both can depend on age, residence, selected options and current terms.
When Essential May Fit—and When It May Not
Essential may be worth checking when you want travel medical protection for an unexpected illness or injury during a defined trip and can satisfy its eligibility and policy conditions.
It may be a poor fit when you need routine healthcare, maternity or cancer care, coverage for an existing condition, guaranteed cashless treatment, or an activity excluded by the offered policy. It is also not proof that a visa application or entry rule has been satisfied.
If your trip includes Hong Kong, Macao or another country, enter the full itinerary and confirm each destination in writing or in the issued certificate. Do not infer coverage from the mainland China portion alone.
Check current Essential eligibility, coverage and price →
When Complete May Fit—and When It May Not
Complete is designed for someone evaluating ongoing international health insurance, not merely a two-week holiday policy. Its broader health categories may be relevant to a long-term nomad or international resident, but application, underwriting, waiting periods, regional selection and the 12-month commitment require more planning.
It is not a last-minute shortcut. SafetyWing says application processing can take up to 10 days, and approved coverage begins according to its stated start-date process. Current policy wording also treats Hong Kong separately within the geographic framework.
Do not assume Complete accepts every applicant, covers a disclosed condition, pays every provider directly or can be cancelled at any time for a full refund. The issued certificate and amendments determine the result.
Check current Complete eligibility, coverage and price →
Claims Checklist for Treatment in China
If you need treatment:
- For non-emergency care, contact the insurer first and ask whether pre-approval or a named provider is required.
- For an emergency, get urgent help and contact the assistance team as soon as practicable.
- Ask the hospital for an itemized invoice, proof of payment, diagnosis, treatment notes, prescriptions and medical reports before leaving.
- Keep transport, accommodation, airline, rail and police evidence for related travel claims.
- Submit through the insurer’s stated channel and respond promptly to requests for more evidence.
- Use the claim deadline printed in your active policy rather than relying on a remembered online summary.
A provider’s published processing time is an estimate, not a guaranteed payout date. Direct billing may be available in some circumstances, but you should remain prepared for an upfront payment request.
Final Buying Checklist
Before paying, confirm all of the following in the live quote and documents:
- your age and residence are eligible;
- the start and end dates cover the entire trip;
- mainland China, every transit point and every side trip are included;
- the medical deductible, maximums and important sublimits are acceptable;
- evacuation and repatriation terms fit your needs;
- all health conditions have been declared correctly;
- every planned activity is included or covered by the required add-on;
- cancellation, delay and baggage benefits match what you expect;
- authorization and claims procedures are practical;
- refund and cancellation rules are understood;
- the 24-hour assistance details are saved offline.
Insurance is only one part of being ready. Use the China Trip Readiness Checker to review entry preparation, mobile internet, payments, accommodation, trains and essential apps before departure.
Official Sources and Review Date
Official sources checked September 28, 2026:
- UK government China health advice
- UK government medical treatment in China guidance
- UK government foreign travel insurance guidance
- UK government China help and emergency information
- SafetyWing Nomad Insurance
- SafetyWing Nomad Insurance FAQ
- SafetyWing Essential policy
- SafetyWing Nomad Insurance Complete
- SafetyWing Complete policy packet
- SafetyWing China care map
Terms, eligibility, geography and official travel advice can change. This guide provides general information, not individualized insurance, medical or legal advice. The policy and certificate issued to you control.